Testament and Islam: what French law allows
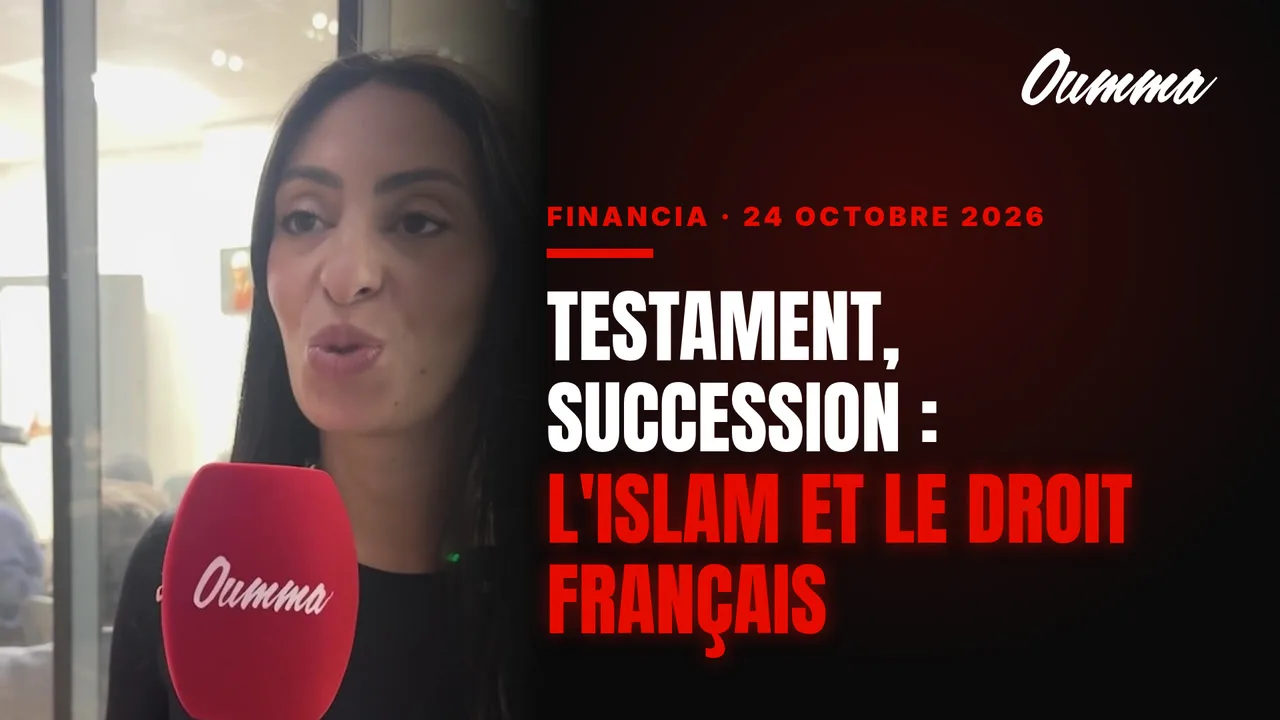
Can you pass on your property according to the rules of Islam when you live and die in France? Salima Dahmani, notary in Montmorency (Val-d’Oise), answered this question in front of Oumma’s camera, on October 24, 2026, at the Financia Business School (Paris 15th). She spoke during “Leading with your values, ethical journey & Islamic finance”, a day organized by students of the 8th promotion of the Certificate of Islamic Finance. His message: the will allows the two rights to be reconciled, provided that French rules are respected.
“Buy, transmit and anticipate your succession”
Salima Dahmani came to “alert” business leaders to a point that is often pushed aside: anticipating the transfer of their business and their assets. For her, Islamic finance goes beyond banking products. “Islamic finance, for our community, is the common thread of our life,” she says, since it involves “applying religious rules in our daily lives.”
The role of the notary, in this context, is to “correlate Islam with a person’s life plans in general: buying, transmitting and anticipating their inheritance”. She cites two examples: wills written “in correlation with Islamic law, but also respecting French rules”, and systems for the purchase of real estate, such as forward payments.
Two logics that do not overlap
Muslim inheritance law itself determines the shares of each heir. The Quran (S.4, 11) attributes to the son a share equivalent to that of two daughters. As Oumma recalled in her series on the reform of inheritance in Muslim law, this unequal sharing only concerns a minority of the cases provided for: in others, the woman inherits as much, or more, than the man. The will is framed by the Sunnah. According to a hadith reported by al-Bukhârî and Muslim, the Prophet refused Sa’d ibn Abî Waqqâş to bequeath two thirds, then half of his property. He admitted the third, specifying that it was already a lot.
French law starts from another principle. Article 735 of the Civil Code provides that children inherit from their parents without distinction of sex or birth order, even if they come from different unions. Without a will, a son and a daughter therefore receive exactly the same share.
Hereditary reserve and available portion: what the law says
The Civil Code protects children through hereditary reservation. Article 912 defines it as the share of property that the law ensures to certain heirs, called reserved heirs. The rest forms the available portion, which everyone can freely dispose of by donation or will.
Article 913 sets the proportions. Gifts cannot exceed half of the assets with one child, a third with two children, a quarter with three or more children. Without children, the surviving non-divorced spouse is reserved for a quarter (article 914-1). Donations made during his lifetime count in this calculation. An injured child can bring an action for reduction in principle within five years following the death (article 921). Since 2021, the notary must also notify each heir whose reservation appears to have been affected that they can exercise this right.
The will itself obeys strict forms. The holographic will must be written in full, dated and signed by the hand of its author (article 970). The authentic will is received by two notaries, or by a notary assisted by two witnesses (article 971).
What a Will Can Do, and What It Cannot Do
The room for maneuver lies in the available quota. Let’s take a theoretical example, without a spouse. A father leaves a son and a daughter. The reserve represents two thirds of the property, shared equally: one third each. The available portion is one third. If he bequeaths it to his son, he receives two thirds and his sister one third. The sharing then corresponds to the Koranic rule, while remaining compliant with the Civil Code.
With three children, two sons and a daughter, the calculation no longer works out. Muslim law would give 40% to each son and 20% to the daughter. French law reserves 25% for each of the three children. The daughter cannot therefore receive less than a quarter, and each son at most 37.5%. The will brings the two rights together, it does not always make them coincide.
The one-third rule can also come up against French law. A bequest from a third party to an association or charity is included in the portion available with one or two children. With three children, the available portion drops to a quarter: the legacy would be reduced. Conversely, other tools partially escape the rules of succession. According to the Insurance Code (articles L132-12 and L132-13), the capital of life insurance paid to a designated beneficiary is not part of the estate and is not subject to reduction, unless the premiums paid were clearly excessive in relation to the subscriber’s means. So-called Sharia-compatible life insurance has existed in France for several years. Their place in a transmission is a matter of personalized advice.
Binational families: the compensatory levy
According to service-public.fr, the law applicable to an inheritance is in principle that of the country of habitual residence, under the European regulation of July 4, 2012. A person can however choose, in a valid will, the law of the State of which he or she is a national.
The law of August 24, 2021 reinforcing respect for the principles of the Republic added a third paragraph to article 913. For inheritances opened since November 1, 2021, if the applicable foreign law does not provide for any reservation mechanism protecting children, each child can make a compensatory levy on assets located in France. Two conditions are added: the deceased or at least one child must be a national or resident of a European Union state at the time of death. The Ministry of Justice clarified the objective in a response to a deputy, published in the Official Journal on November 21, 2023: to prevent a parent from discriminating against their children born from different unions, or excluding some of them because of their sex, their birth order, their parentage or their religion.
The system was contested in Brussels, especially by British owners in France. In a letter dated June 4, 2026, the European Commission took note of the French interpretation: the levy does not apply if foreign law provides for a child protection mechanism, even different from the French reservation. According to the specialist blog EAPIL, the Commission closed the procedure on July 28, 2026.
“We do it with the tools we have”
“In reality, in the notary profession, in general, we work with the tools we have, and we apply ourselves to clients’ situations according to their particularities,” she explains. “So if the particularity is to respect values and ethics, well we will do so, while respecting French laws. »
This framework is not specific to France. Morocco, for example, opened the profession of adoul, the notarial profession under Muslim law, to women, and Tunisia debated equality in inheritance. In France, the answers are constructed on a case-by-case basis, at the notary, based on the number of children, the presence of a spouse and the nationality of each.
Find the full report and the other speakers of the day in our article Leading with its values: Islamic finance at the service of business leaders.
